Key Takeaways
- Ask for itemized prices and select the arrangements you want rather than assuming a package is required.
- Check available funds and assistance before deciding whether any borrowing is necessary.
- Borrowing more than the verified gap is not automatically prudent.
Start with the arrangements and a spending limit
Funeral decisions often arrive under pressure. Before applying for credit, list the arrangements being considered and who has authority to approve and pay for them. Check available funds, any existing prepaid arrangements, insurance or possible assistance, including when money would actually become available. Do not commit on the assumption that a benefit or reimbursement is guaranteed.
Set a provisional spending limit and ask another trusted person to help compare written prices if that is useful. A more expensive service is not a measure of respect for the person who died.
Use the FTC’s itemized-price protections
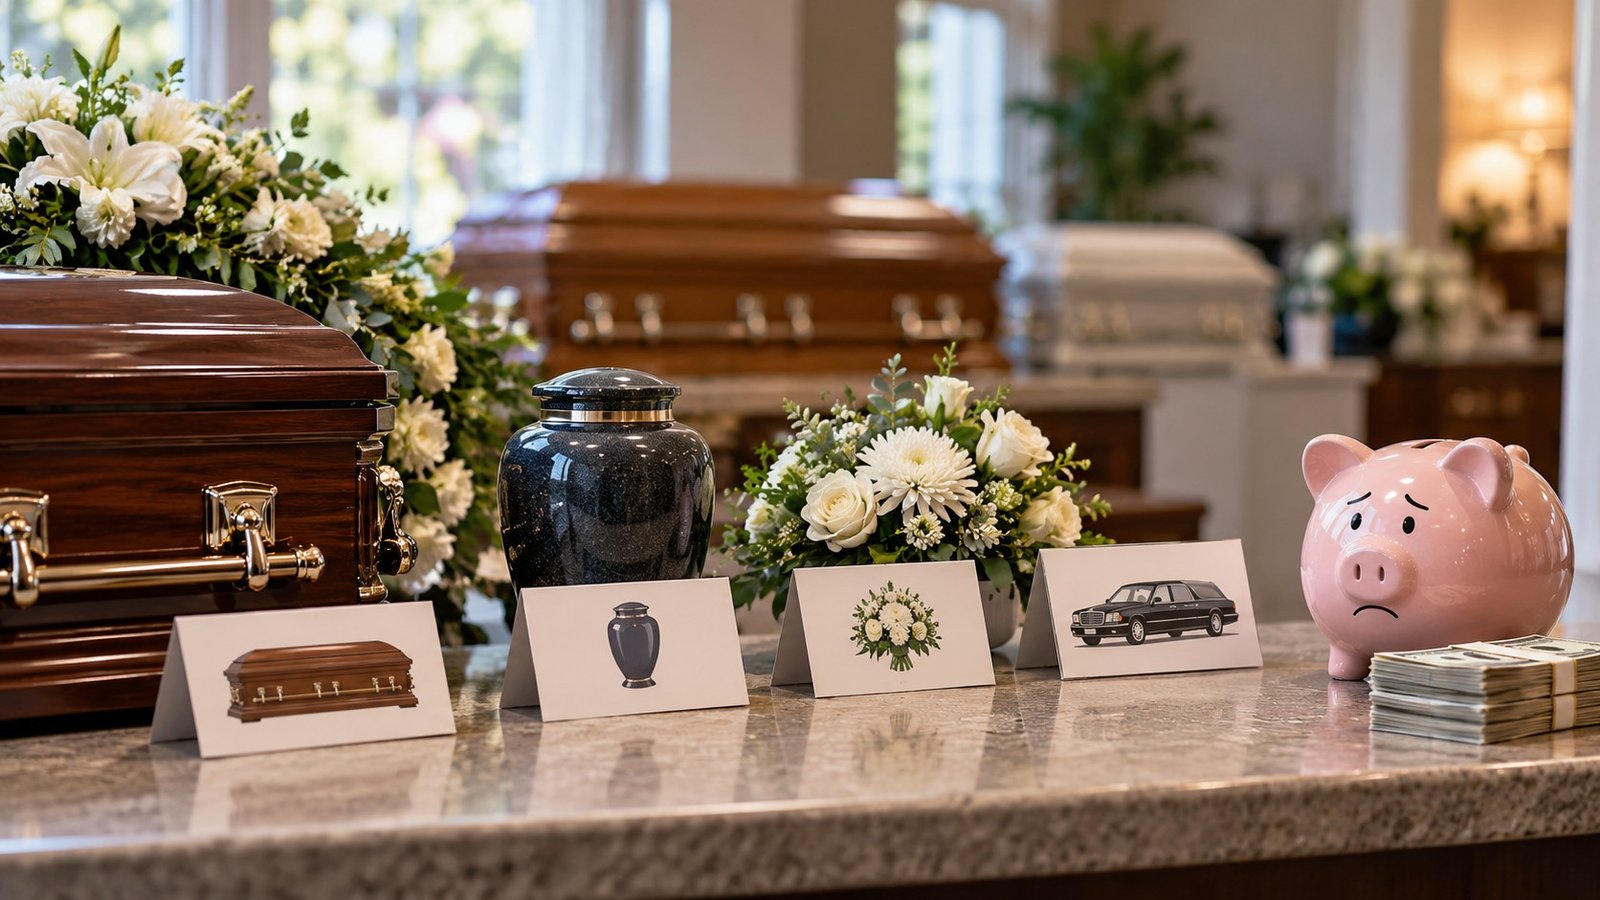
The FTC Funeral Rule generally lets you select individual goods and services from covered funeral providers instead of accepting a package. The FTC says providers must give price information by telephone, a General Price List when you visit, and an itemized statement after arrangements are selected and before payment.
The Rule has scope limits: it does not cover third-party sellers or cemeteries without an on-site funeral home. Ask separately about cemetery, crematory and other third-party charges. Request a written explanation of any claimed legal or cemetery requirement.
Calculate the actual funding gap
Add the selected costs and subtract confirmed funds available by the payment deadline. Ask the provider about lower-cost alternatives and payment arrangements. The FTC explains that routine embalming is not universally required and that alternatives can exist; state rules, timing and the chosen arrangements matter.
Do not follow a rule to always borrow slightly more. Extra principal adds debt and can increase interest. If a cost remains uncertain, identify it and obtain a written estimate rather than treating an oversized loan as the default solution.
If borrowing remains necessary
- Compare APR, fees, cash received and total scheduled repayment.
- Check whether the payment fits after essential household bills.
- Identify any collateral, cosigner obligations and consequences of missed payments.
- Confirm the actual funding and provider-payment deadlines.
- Avoid promises of guaranteed credit in exchange for an advance payment.
No particular lender, credit-score threshold or funding speed is endorsed here. Keep price lists, contracts and payment records so the agreement can be reviewed later.
Sources and review limits
FTC Funeral Rule consumer guidance (July 2012 page, checked October 25, 2026) and CFPB personal-loan fee guidance (reviewed August 30, 2024). General education; eligibility, costs and legal or tax outcomes depend on the applicable terms and your circumstances.
Continue reading
Check an emergency-loan offer and review household estate-planning records.